

What personal contract purchase actually is
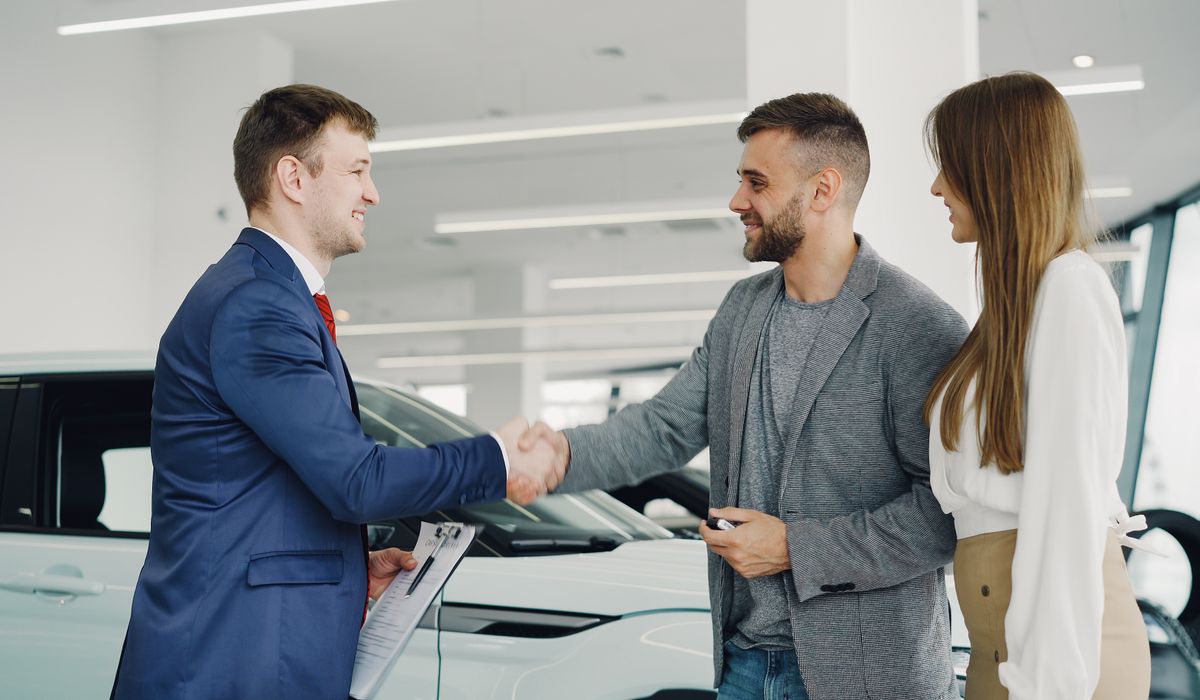
Personal contract purchase, almost always shortened to PCP, is the finance deal that made new cars feel affordable to a generation of London drivers. Instead of paying for the whole car, you pay for the portion of its value you expect to use over the term – typically two to four years. The rest is deferred into a final payment known as the balloon or optional final payment, which you only settle if you want to keep the car outright.
At the end of the agreement you get three choices. Hand the keys back and walk away, provided you have stayed within your mileage cap and the car is in fair condition. Trade it in against something newer, using any equity above the balloon as a deposit. Or pay the balloon and own it. That flexibility is genuinely useful, but it only works in your favour if you understand the numbers before you sign, not after.
Monthly payments look small for a reason
PCP monthly payments are lower than a hire purchase or personal loan for the same car because you are not paying off the full price. A car that costs £28,000 might have a balloon of £12,000 after three years, so your instalments only cover roughly £16,000 plus interest. On a three-year term that could mean monthly payments several hundred pounds lighter than buying outright on finance.
Before you get comfortable with that figure, add up what PCP really costs:
- Deposit – often 10 per cent or more, sometimes with a manufacturer contribution on top.
- Monthly payments for the full term, with interest charged on the amount financed.
- Final balloon payment if you want to keep the car.
- Any mileage or condition charges at hand-back.
Add those together and compare the total against the car's cash price. PCP is rarely the cheapest way to own a car outright, but it can be a sensible way to drive a newer one within a set budget.
Mileage limits matter more in London than you might think
PCP agreements quote an annual mileage allowance, commonly 8,000, 10,000 or 12,000 miles. Exceed it and you pay an excess mileage charge, usually somewhere between 6p and 30p per mile depending on the deal. That sounds trivial until you do the arithmetic. Running 4,000 miles over a 10,000-mile allowance at 15p per mile is a £600 bill on the day you hand the car back.
London drivers often assume they will do low mileage, and many do. Congestion Charge, the Ultra Low Emission Zone and the difficulty of parking all discourage unnecessary trips. But a couple of weekend breaks to the coast, regular trips to see family up north, or a job change that adds a motorway commute can quietly push you past your cap.
Be honest about your driving patterns when you set the allowance. If you are unsure, it is usually cheaper to pay slightly more each month for a higher cap than to face a lump-sum charge at the end. Ask the dealer what the excess mileage rate is before you commit, and get it in writing.
Wear and tear, and the fair wear and tear standard
When you return a PCP car, it is assessed against a published fair wear and tear guide. Dents, kerbed alloys, torn upholstery and cracked glass can all lead to reconditioning charges. London parking is unforgiving, and a scuffed bumper from a tight bay is far more likely here than in a rural county.
Look after the car as though you owned it outright. Keep up with servicing, use the recommended parts, and repair minor damage as it happens rather than letting it accumulate. A tidy car with a full service history is far easier to hand back without argument, and it may also be worth more as a trade-in, giving you equity towards your next deposit.
Is PCP the right fit for you?
PCP tends to suit drivers who want a new or nearly new car, like the certainty of a fixed monthly payment, and are happy to change vehicles every few years. It works especially well if you can put down a reasonable deposit, keep within your mileage, and either walk away or roll into another deal.
It is a poor fit if you plan to keep the car for a decade, expect to cover high mileage, or want to modify it. It is also a poor fit if the monthly payment is only affordable because you have stretched the term to five years and the deposit to the very limit of your savings. A car should not be the reason you have no emergency fund.
Read the agreement carefully. Check the APR, the total amount payable, the balloon figure, the mileage terms and the early settlement rules. If the numbers make you uncomfortable, ask about hire purchase or a bank loan instead – a smaller, older car bought outright is often the cheaper long-term decision.


John Doe
14 January, 2022Having no content in post should have adverse..
Chauffina Carr
10 April, 2022We use these tests all time! Killer stuff!
Jim Séchen
16 July, 2022Thanks for all the comments, everyone!